Assistance CleanTechnica’s work through a Substack subscription , on Patreon , or on Stripe Help us generate all of the top quality, original content we publish week after week regardless of the challenges of content-scraping AI, antisocial media, inflation, and other hurdles.
For years, I have been writing that the insurance policy market will strongly affect the environment alter argument, since its goal it to identify dangers and price its plans appropriately. You can not build a brand-new 80 story tower packed with luxury condos on the side of a sea if you can’t get insurance, right? You can not build a new 5, 000 square foot house on a flooding plain if you can not get insurance policy, can you?
According to a brand-new report from Inside Track , a group of senior insurance policy industry professionals, all our assumptions concerning the insurance market can be discarded. Someone when said business version for insurance companies is to sell coverage and refute responsibility. Now there is a brand-new crease– selling coverage that omits climate dangers. Below I believed these expert risk supervisors would compel the remainder people to confront the existential threats we encounter, but that evidently isn’t so. Just like every other organization, they are content to take our cash while providing us less and much less security.
The insurance policy professionals at Inside Track composed, “We are worried that the risk degrees we are seeing either aren’t being interacted to or aren’t being properly internalized by federal government. Without intervention, these physical threats will translate right into significant financial risk. The undermining of the home mortgage market drove the Global Financial Dilemma. We are stressed a significant boost in without insurance, high-risk properties might manifest in a comparable method as environment impacts escalate.”
Don’t Inform Any Individual!
This is some sturdy stuff. Fundamentally, what the Inside Trac individuals are saying is that some in the insurance coverage industry are reducing the information they have so their clients are not familiar with the dangers they face. If this sounds to you like the oil and gas industry existing to us for the past 60 + years regarding the injury using their products triggers, you are stone’s throw wrong. Right here’s more from Inside Track:
If you being in board conferences at major insurance firms, you may expect that these issues would go to the leading edge of the agenda. In reality, they barely make the top 3 most pushing concerns being discussed. Why? Due to the fact that the sector is positive in its strategy to react in such a way that handles its direct exposure– namely to
First: reprice, leaving insurance expensive to many.
Second: alter or restrict coverage by getting rid of wildfire coverage from buildings insurance policy, for example.
Third: merely take out provision (of insurance policy) from particular industries, geographies, and areas, consisting of several farming areas upon whom society depends.
This process has already started and will certainly currently accelerate. The web outcome will be a boost in without insurance losses for which somebody else will certainly have to pay the rate. This is not as a result of any malevolence of insurance firms however because this is just how our market is incentivized to operate if we focus on the short term.
Whilst the sector’s action to physical threat is readily logical over this short term horizon, it develops a scenario that needs to be of deep issue to any person concerned concerning economic stability and the experience of the areas — consisting of lots of clients these days — who will encounter the strongest effects of environment adjustment.
The High Cost Of Long Term Threats
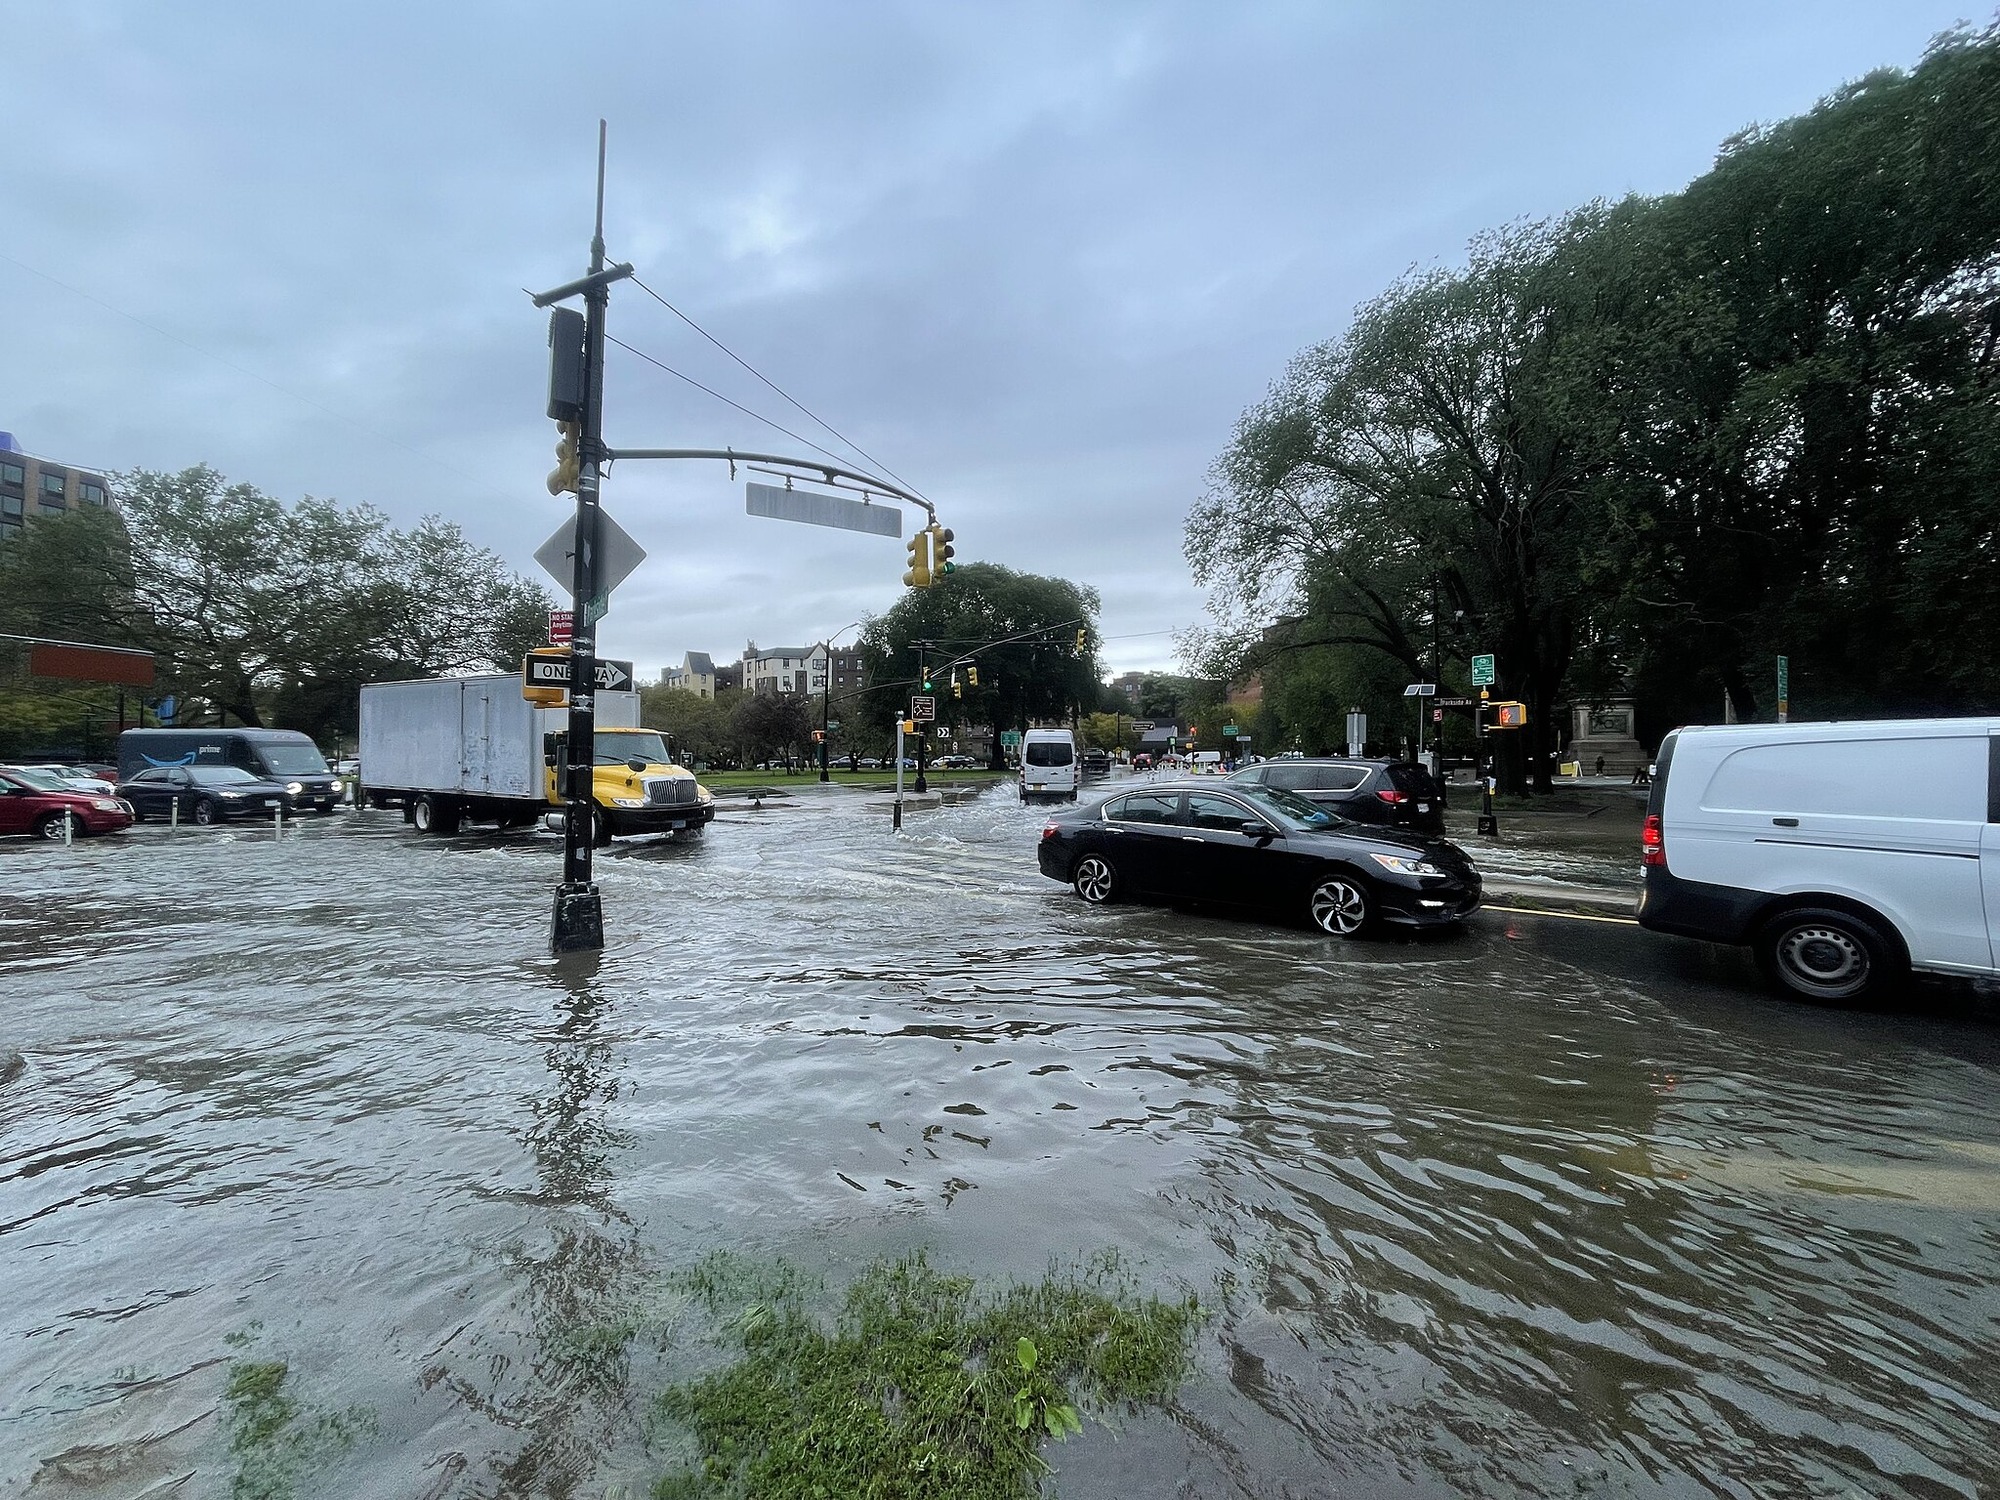
Bloomberg reported on October 13 that Amanda Blanc, the CEO of Aviva Insurance coverage, claims that homes being constructed in the UK today are already uninsurable as a result of the boosting threat of flooding Günther Thallinger, a director at Allianz, has actually claimed “whole areas” risk becoming uninsurable as a result of environment adjustment.
Nicholas Stern, chair of the Grantham Study Institute on Environment Adjustment at the London Institution of Business economics, told Bloomberg, “Individuals that price risk for a living are alerting, from the inside, that our versions have actually undervalued the risk. And that mis-priced danger is building to potentially unmanageable levels.”
Anthony Hobley worked as the replacement chair for environment threat and durability at Howden Group Holdings up until just recently. On LinkedIn he recommended that component of the problem is that the insurance policy market typically creates policies for just one year, a technique that essentially conceals longer term risks. “Our pricing skill is only ever released twelve months each time. It does not aid clients handle danger over the long term, or stay insurable,” he claimed.
Viewers are currently conscious that State Ranch has actually responded to losses from wildfires in California by getting rid of coverage from its plans for homeowners because state. State Farm might be like an excellent next-door neighbor if your sink leaks and damages your kitchen area, but if your home is damaged by wildfire … well, it sucks to be you. Exactly how’s that for being neighborly?
Individuals residing in Florida and Louisiana are finding that hurricane insurance expenses 3 times as much as it carried out in 2023– if you can locate a company that provides insurance coverage whatsoever. In Florida, many condominium organizations are required by regulation to have wind and flood insurance policy , yet the state has done little to make certain inexpensive protection is available to them.
Adjustments In The Insurance Industry
Inside Track put the issue quite clearly when is stated, “Instead of do something about it to help federal government recognize and minimize environment threat or assist the public pertained to terms with the influences dealing with different areas, from farming regions to coastal, hilly and wildfire susceptible areas, we are seeing our sector turn more insular.
“In some (but not all) firms, those raising these issues are coming under increasing stress. For instance, natural catastrophe modelers and actuaries are being asked to offer a ‘hairstyle’ to future estimates or ‘handle down the numbers’ in order to avoid causing alarm system and to keep getting bargains done.
“Our market grows in settings where threats are reasonably foreseeable. We are moving right into a globe that is far from predictable and we are neither ready ourselves or moving to prepare our consumers these days, who might instantly discover that they are not our consumers tomorrow.”
Capitalism And Its Unhappiness
At the heart of the matter is the age old truisms of a capitalist economic climate. Cities and towns can only raise their profits by means of tax. When a programmer suggests an 80 story structure filled with deluxe condominiums on the side of the ocean, the local government sees dollar signs. It will after that press the insurer to create a plan that will certainly satisfy loan providers that want to fund that chrome and glass monstrosity. Some insurance company someplace will be just to delighted to take the money and bet it won’t have to pay a case for at the very least one year.
The outcome is that long term danger gets lessened. The city government sees an increase in tax obligation earnings. The specialist earns a profit on the building. Lenders make a profit on their investment. And insurer earn a profit from the costs they bill. Prices in long-term threat short circuits the gravy train for everybody, and we can’t enable that to occur, now can we?
Greed Is Bad
Where I live in Florida, there is an inlet that attaches the Indian River Lagoon to the Atlantic Ocean. As I am driving north on A 1 A towards the inlet, it is not uncommon to see a yacht crossing my line of vision. For a moment, it resembles it is moving along the very same sidewalk I am driving on. Couple of people ever stop to consider that the degree of the water in the inlet is virtually equal to the elevation of the street and what that suggests for the future.
And yet, the city I live in is drooling over the possibility of a 500 room resort a programmer wants to build just 10 feet from the edge of the inlet. All it can consider is all the wonderful tax obligation revenue it will get if that hotel gets constructed. Greed really is the root of all bad and will likely prove to be the downfall of the human race. We stop working to take a clear eyed view of the future at our peril.
Sign up for CleanTechnica’s Weekly Substack for Zach and Scott’s comprehensive analyses and high degree summaries , enroll in our day-to-day newsletter , and follow us on Google Information
Have an idea for CleanTechnica? Want to promote? Intend to suggest a guest for our CleanTech Talk podcast? Call us below
Enroll in our day-to-day newsletter for 10– 15 brand-new cleantech stories a day Or register for our weekly one on the top tales of the week if daily is as well constant.
CleanTechnica uses affiliate links. See our policy right here