This is a section from the 0xResearch e-newsletter. To review full editions, subscribe
The headline in crypto today is Less heavy’s LIT token ultimately going live, noting a vital minute in the continuous battle for perps market share. In today’s insurance coverage, we break down among the most neglected recipients of perps growth (Pendle via Boros), and take a more detailed check out the advancing dynamics within the Solana liquid-staking landscape.
Indices
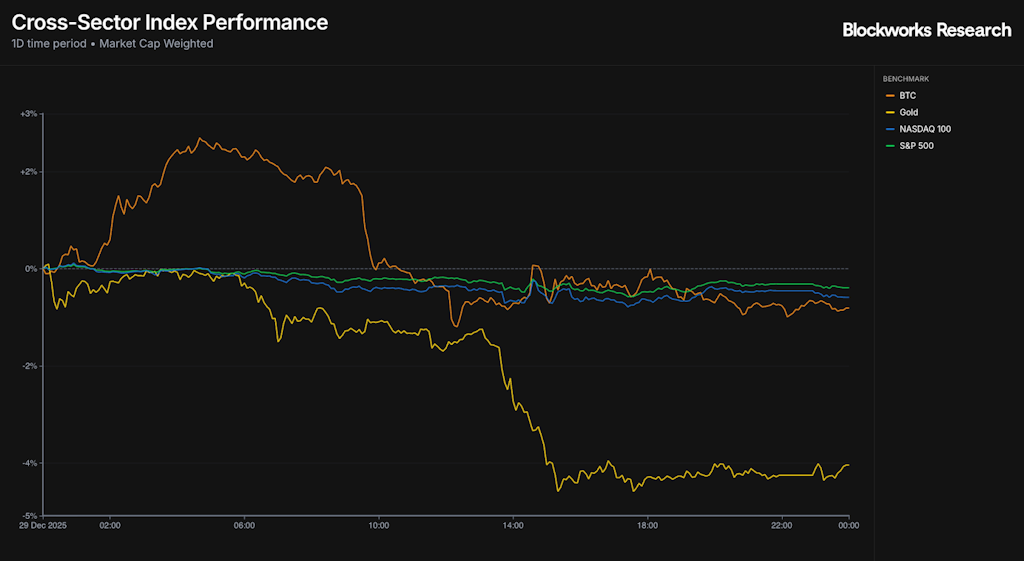
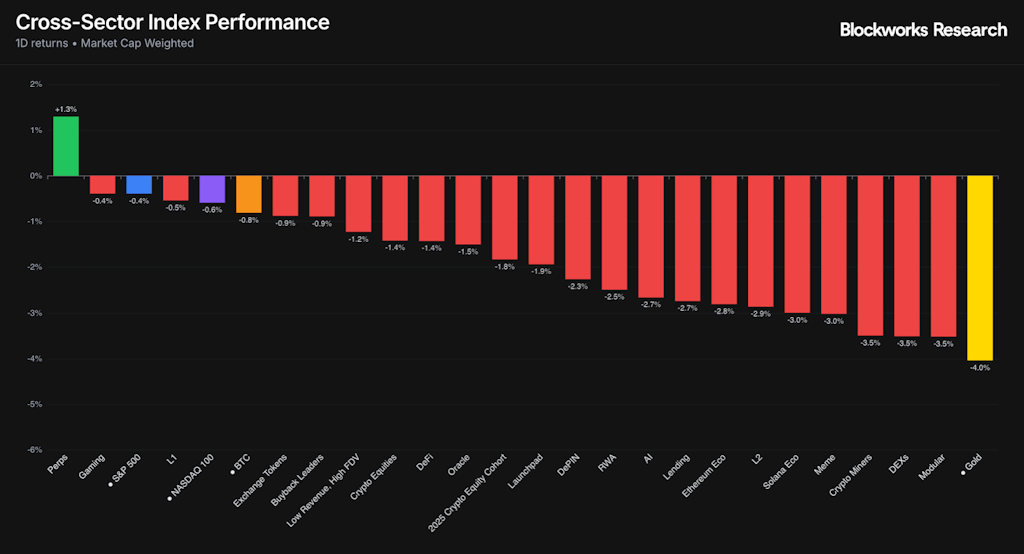
Markets kicked off the last week of the year on a softer note. Bitcoin (-0. 81 %) underperformed its United States equity benchmarks, with the Nasdaq (-0. 59 %) and S&P 500 (-0. 39 %) publishing moderate pullbacks after technology stocks drove the S&P 500 to all-time highs recently. Meanwhile, Gold (- 4 04 %) and other rare-earth elements saw a sharp selloff in the middle of profit-taking, after having been standout performers in the past few weeks.
Back on the crypto front, Perps (+ 1 3 %) was the only index to complete the day in the eco-friendly, with buzz leading gains in advance of Less heavy’s TGE today. Competition for perps market share has actually warmed up in recent months. Lighter has actually revealed that verifiable execution and absolutely no retail fees can drive market-leading quantity, leading perps trading with simply over $ 200 billion in quantity over the past 30 days, followed by Aster ($ 172 billion) and Hyperliquid ($ 161 billion). That said, Hyperliquid remains the just one of the three operating without energetic motivations and is the clear profits leader, creating ~$ 47 million over the same period.
The real test will be whether Lighter can hold its volume lead after TGE, particularly with several connecting its current rise to points farming. In a news thread last night, the group laid out the token framework and airdrop details, noting that “the worth created by all Lighter services and products will completely accumulate to LIT holders” which the labs entity will certainly operate at expense. Token circulation is divided in between community (50 % of overall supply) and team/investors (continuing to be 50 %), with 25 % of overall supply airdropped to factors holders from Seasons 1 and 2
As of creating, LIT is trading at a flowing market cap of $ 695 million and an FDV of $ 2 8 billion. Per DeFiLlama, the method has generated $ 8 76 million in profits over the past 30 days ($ 105 million annualized), implying LIT trades at a P/S of ~ 7 x and an FDV/Sales of ~ 27 x.
Market upgrade
While every person is active debating that will certainly win the perps race (mostly Hyperliquid vs. Lighter babble after Less heavy’s TGE), one of the most interesting recipient might be concealing in ordinary view: Pendle, by means of Boros. In my sight, Pendle stands to gain from the structural growth and fostering of continuous futures, regardless of that eventually controls, on either CEX or DEX rails.
Pendle introduced Boros in very early August 2025, offering DeFi a brand-new onchain monetary primitive: rates of interest swaps. One can think about Boros as a perps exchange itself, however with two essential spins. Initially, instead of banking on the rate activities of possessions, one is banking on the motions of return. Second, while perpetuals (as the name recommends) have no expiration, Boros markets have a maturation date.
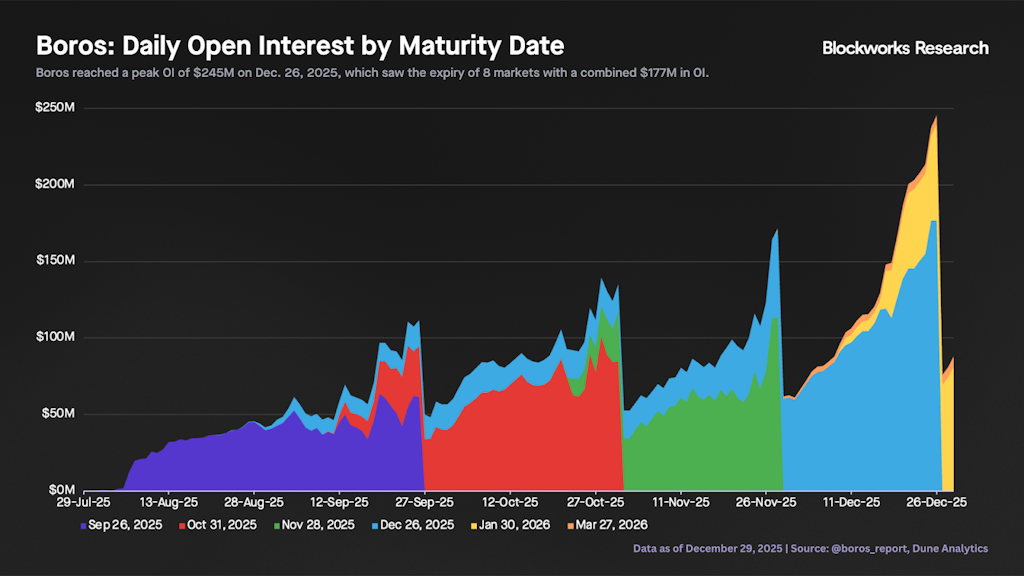
Although Boros has presented progressively, very early traction has been strong. As displayed in the chart below, daily open interest (OI) by maturity came to a head at $ 245 million on Dec. 26, 2025, when 8 markets with a consolidated $ 177 million in OI expired. The growth pattern in OI is extremely intermittent, similar to Pendle v 2, reflecting the all-natural peaks and troughs around the maturities and redemptions integral to yield markets.
Concerning its hidden auto mechanics, Boros allows trading of funding rates by producing something called a Yield System (YU). For those familiar with Pendle v 2 markets, YU resembles the Return Token (YT), and represents the future return of an underlying property up until its maturity. Investors can either go long or short the YU.
- Lengthy placement: If a trader is long 2 YU-BTCUSDC-Hyperliquid at 10 % suggested APR, they are devoted to paying a 10 % set price, while obtaining the underlying APR (financing price settlements) comparable to a 2 BTC placement in Hyperliquid BTCUSDC.
- Brief position: In a short setting, the trader would certainly dedicate to paying the floating underlying APR in return for a dealt with APR, determined by the typical implied APR at the time they went into the position (10 % in this example).
On Boros, rates are settled regularly at the very same time as the underlying exchange’s financing price settlement. For instance, funding rates on Binance are worked out every eight hours, so prices on Boros for the Binance pools are additionally cleared up every eight hours. Likewise, Hyperliquid funding rates are cleared up per hour, and Boros prices for these swimming pools follow the very same hourly negotiation timetable. At maturity (or when the placement is shut), if the ordinary Hidden APR > ordinary implied APR upon entry, a lengthy placement will make money and the other way around.
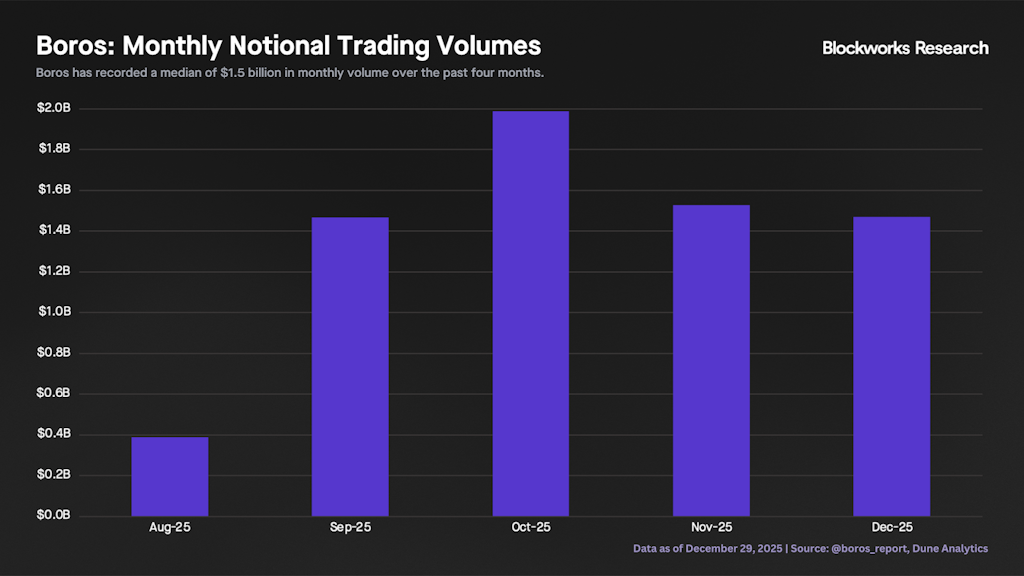
Beyond OI, which presently rests at ~$ 88 million, one more key metric for Boros is notional trading volume. As shown in the chart below, Boros has actually refined approximately $ 6 8 billion in advancing quantity since launch, with a mean monthly quantity of around $ 1 5 billion over the previous 4 months.
Boros has two primary charge sources: (1 a flat cost on top of the indicated APR for every swap, which differs by market, and (2 a flat charge of 0. 2 % of the dealt with APR side of every YU throughout settlement. The chart listed below programs that Boros has generated ~$ 300, 000 in cumulative profits since inception, balancing ~$ 67, 000 in regular monthly profits over the past 4 months. Of note, liquidation fees continue to be unimportant, totaling up to ~$ 1, 300 since beginning.
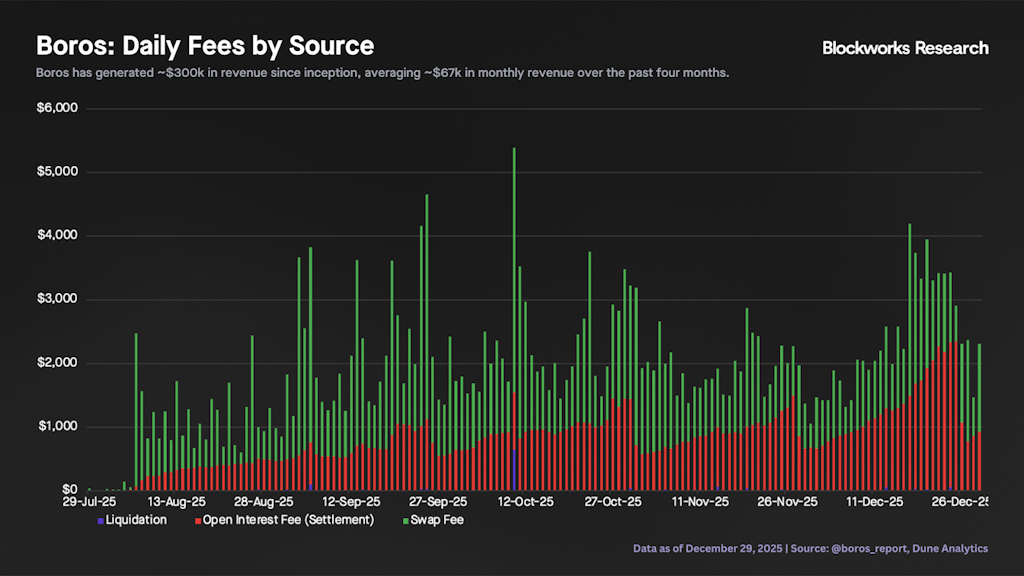
Swap costs correlate with notional trading quantity. In a market with a swap cost tier of 0. 05 %, investors will certainly make money if indicated APR modifications by greater than 0. 1 % in their support (assuming no return negotiation), as investors will certainly need to open and shut the placement, thus incurring 2 x the swap fee. On the various other hand, OI charges (0. 2 % of the repaired APR during negotiation) follow the intermittent growth patterns of Boros’ OI.
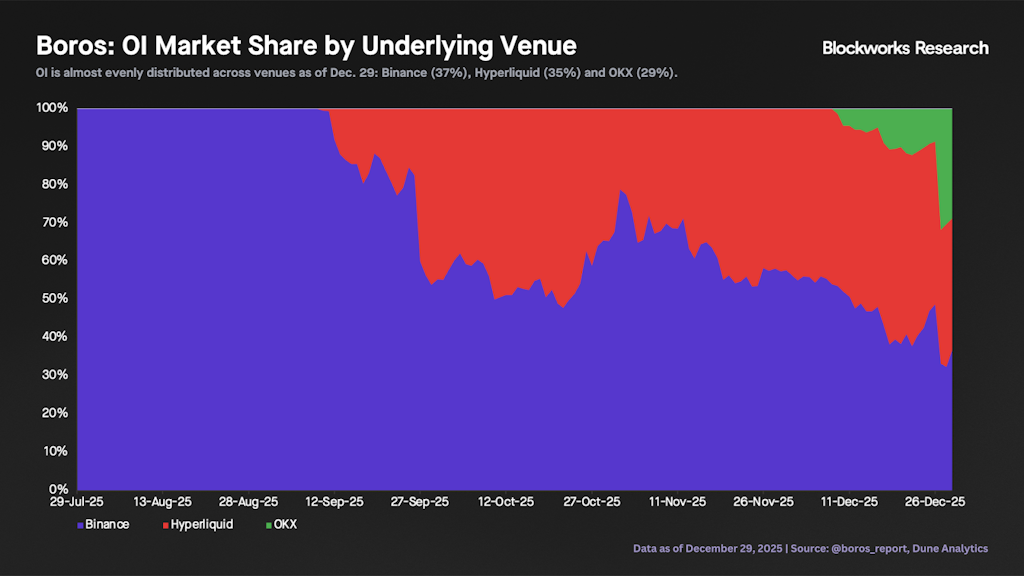
While the bull instance for Boros is that it becomes DeFi’s default rate of interest derivatives place (expanding beyond financing rates to stablecoin returns, cash market rates, LST yields and more), its biggest possibility over the following 6 to twelve months is directly in the perpetuals vertical. Boros launched with just BTCUSDT and ETHUSDT perps markets on Binance in August, yet has actually considering that broadened to additional places (Hyperliquid and OKX) and possessions (HYPE). The chart below programs that OI was dominated by Binance early on, but is now almost equally dispersed throughout locations as of Dec. 29: Binance(37%), Hyperliquid (35 %), and OKX (29 %).
Concerning asset dominance, the ETH-USD market continues to be the biggest on Boros by OI, adhered to by BTC-USD and HYPE-USD.
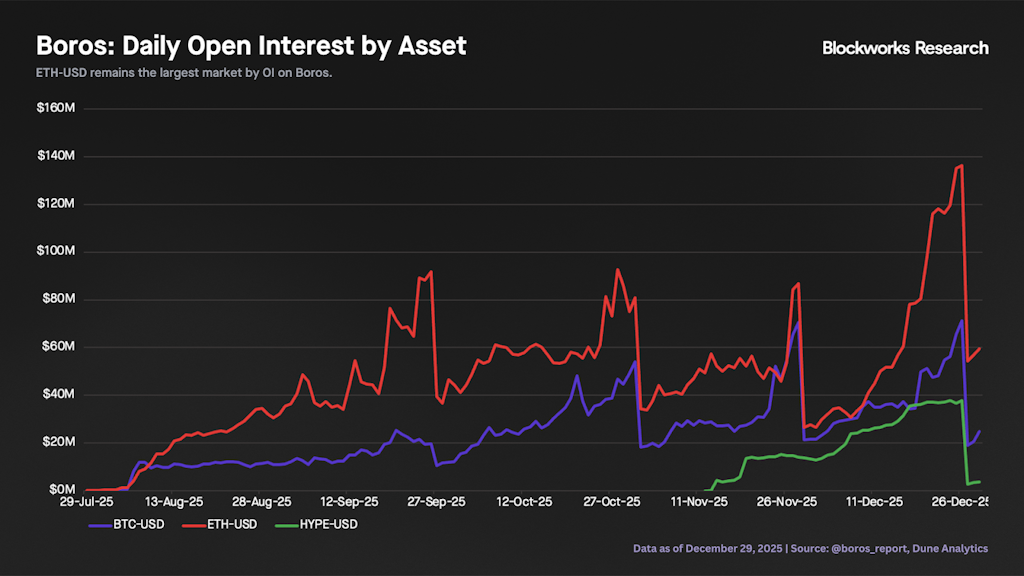
A vital benefit of Boros is that it gains from the maturation of perpetuals without being tied to any kind of single venue, considering that it can support multiple exchanges and properties. As much more sophisticated participants go into the perps space, they’re most likely to require strategies that Boros distinctly enables: hedging funding payments on a lengthy setting, hedging funding receivables on a brief position, or carrying out cash-and-carry professions. Looking in advance, as perps gain regulative acceptance and more typical firms trade RWA perps like equities and products, these gamers will intend to trade YUs of TSLA, gold and thousands of other properties on Boros.
Today, Boros stands for much less than 5 % of Pendle v 2 earnings, however it is well-positioned to be the most crucial growth vector for the method and may eventually rival or surpass v 2 gradually.
Obtain the news in your inbox. Check out Blockworks newsletters: